Harry Potter and the Chamber of Down Payment Secrets: The Magic of 10%
Published on October 25, 2026
How much down payment should you make when buying a home? Many buyers already know that a bigger down payment reduces their mortgage and future interest. But there is another way to save thousands that you might not know about.
My advice for buyers planning less than 10% down is simple: Before you settle for 5%, 7%, 9% or even 9.99%, check whether you can reach 10%. The reason is mortgage default insurance, commonly called CMHC insurance.
Why Does 10% Down Matter?
Most Canadian homebuyers with less than 20% down need mortgage default insurance. It protects the lender, not you, and its premium is generally added to your mortgage.
For a standard eligible owner-occupied purchase with an amortization of 25 years or less, CMHC's premium rates are:
| Down Payment | Standard CMHC Premium Rate | Rate Reduction |
|---|---|---|
| Below 10%* | 4.00% | 0% |
| 10% to less than 15% | 3.10% | 0.90% |
| 15% to less than 20% | 2.80% | 0.30% |
| 20% or more | 0%* | 2.80% |
*The minimum permitted down payment depends on the property's price. At 20% or more, default insurance is generally not required, so 0% represents an uninsured mortgage with no premium. Some conventional mortgages may still be insured. Rate reductions show percentage-point changes at each threshold, not a relative percentage discount. Actual insurance rates can vary with eligibility and mortgage features.
What If You Put 9.99% Down Instead of 10%?
Imagine you are buying a home for $650,000. You have almost 10% saved, but you stop at 9.99%. What happens if you add just a little more?
| Comparison | 9.99% Down | 10% Down |
|---|---|---|
| Down payment | $64,935.00 | $65,000.00 |
| Mortgage before insurance | $585,065.00 | $585,000.00 |
| CMHC insurance rate | 4.00% | 3.10% |
| Insurance premium | $23,402.60 | $18,135.00 |
| Total mortgage including premium | $608,467.60 | $603,135.00 |
Yes, in this example, an extra $65 toward your home reduces your insurance cost by $5,267.60. The extra down payment becomes home equity; the $5,267.60 is the actual reduction in the premium. That lower mortgage balance may also reduce the interest you pay.
What About 9% Down?
Even if you are not quite as close to 10%, it is worth checking the numbers. On the same $650,000 home, a 9% down payment is $58,500 and the standard insurance premium is $23,660. At 10% down, the premium is $18,135.
What About 15% and 20% Down?
At 15%, the standard premium rate falls again, from 3.1% to 2.8%. The bigger opportunities, however, are often at 10%, where the rate falls by almost one percentage point, and at 20%, where mortgage default insurance is generally not required at all.
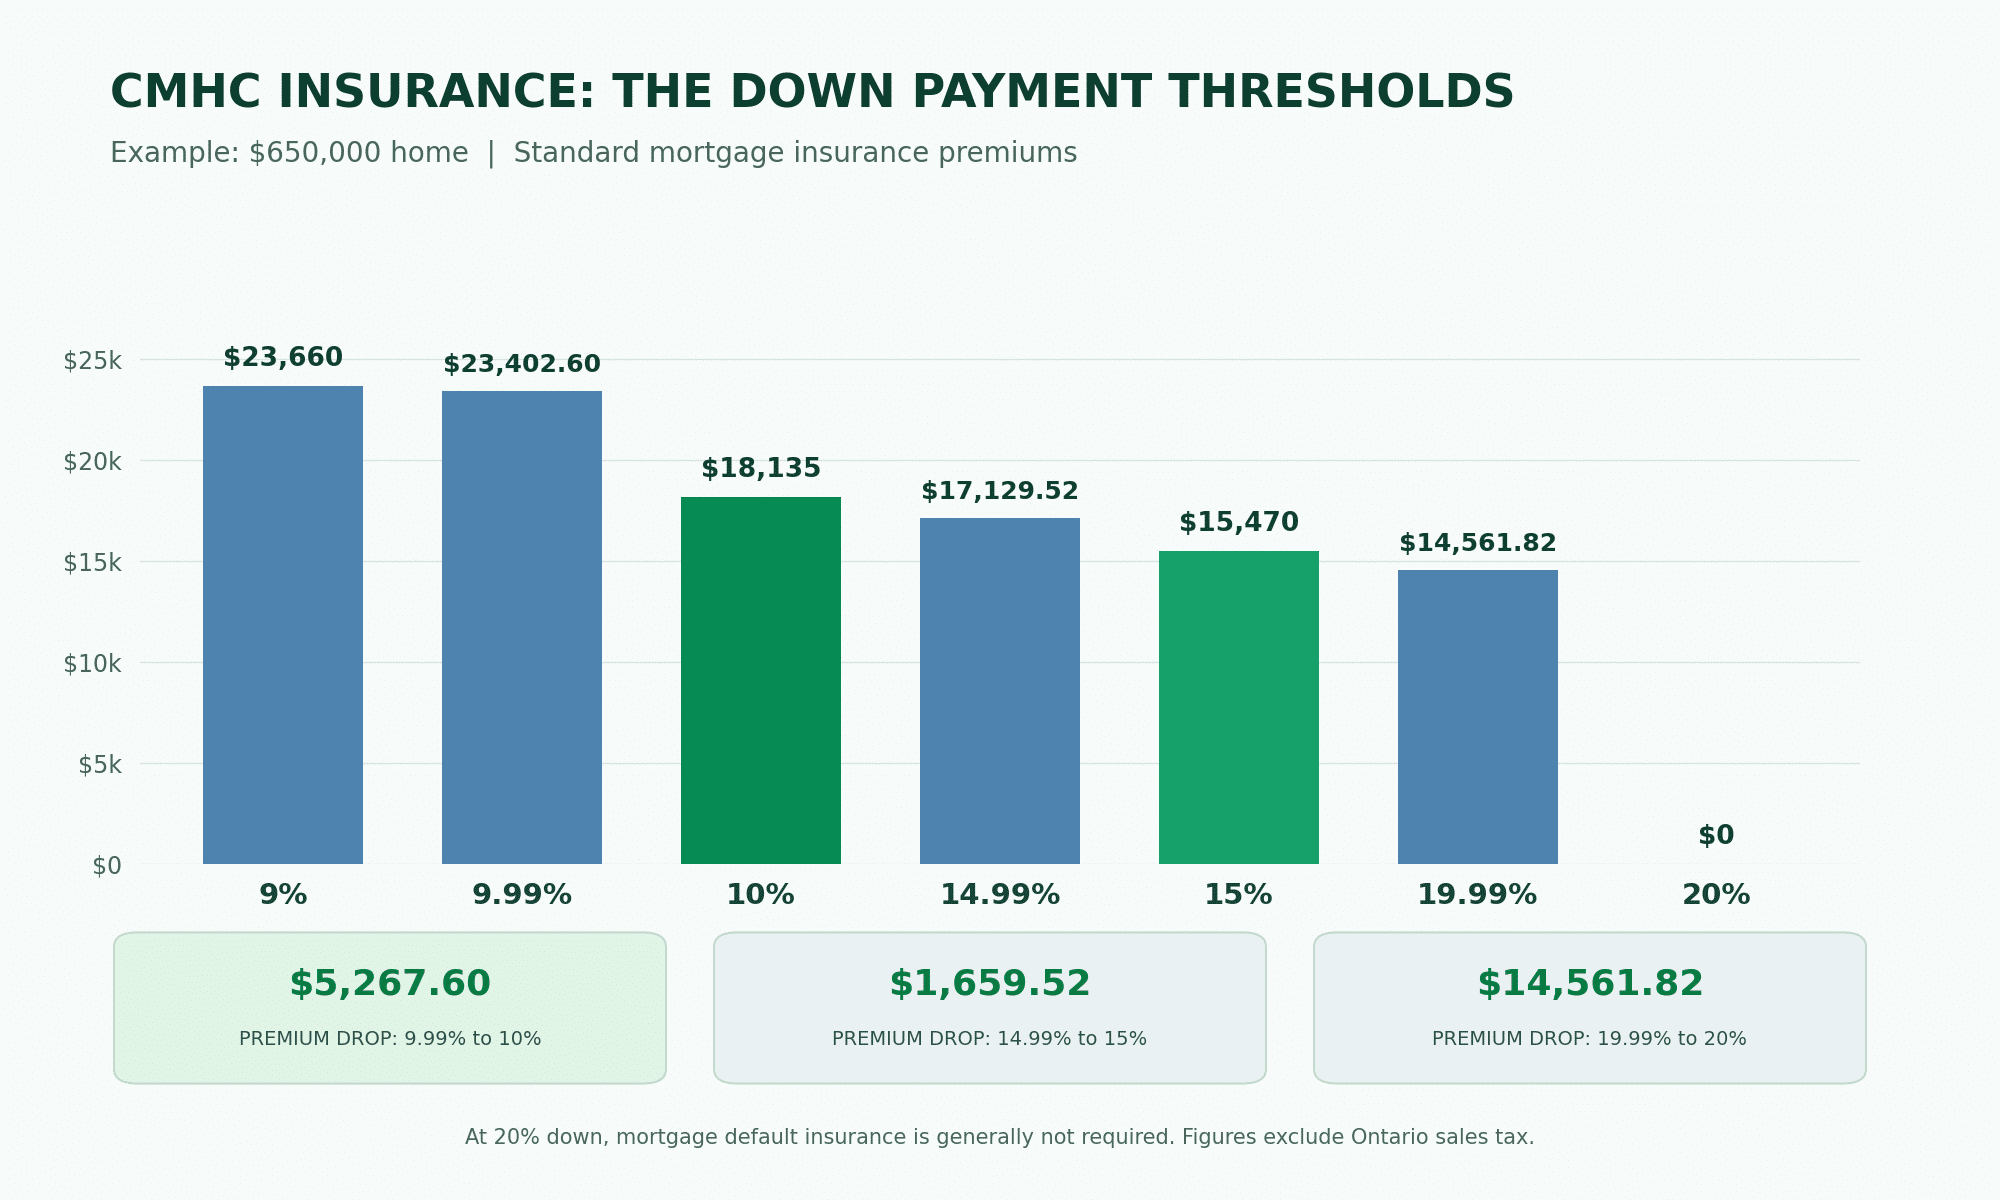
Illustrative standard CMHC premiums. *At 20% down, this example assumes no default insurance is required.
Should You Always Try for 10% Down?
Check the numbers before deciding. If you are below 10%, reaching that threshold could be worthwhile. But don't empty your savings to do it. You still need money for closing costs and emergencies. In Ontario, the 8% provincial sales tax on the insurance premium is generally paid at closing, not added to the mortgage.
Also, if you need to borrow money to reach the threshold, remember that borrowed down payments are subject to lender and insurer rules and may create additional costs.
The Bottom Line
- Less than 10% down? See if you can reach 10%.
- At 10%, the standard CMHC premium rate drops from 4% to 3.1%.
- On our $650,000 home example, moving from 9.99% to 10% down means just $65 more upfront and $5,267.60 less mortgage insurance.
- Keep enough savings for closing costs and emergencies.
Don't choose your down payment percentage without looking at mortgage insurance. This is one area where a small difference in percentage can make a surprisingly big difference in cost.
Before deciding how much down payment to make, try my Down Payment & Mortgage Insurance Calculator. You can compare different down payment percentages and see exactly how they affect your mortgage insurance premium.
Calculations use standard CMHC owner-occupied mortgage loan insurance premium rates for an eligible purchase with an amortization of 25 years or less. Premiums are calculated on the mortgage amount before insurance and are illustrative. Certain mortgage products, longer amortizations and eligibility conditions may produce different costs.
CMHC: Mortgage loan insurance cost
Ontario: Retail sales tax on insurance premiums
How Much Down Payment Should You Make?
Try your planned down payment, then compare it with 10%, 15% and 20%. See how your insurance premium and total mortgage change.
Calculate My CMHC Insurance Savings →