Should You Break Your Mortgage for a Lower Interest Rate?
Published on October 15, 2026
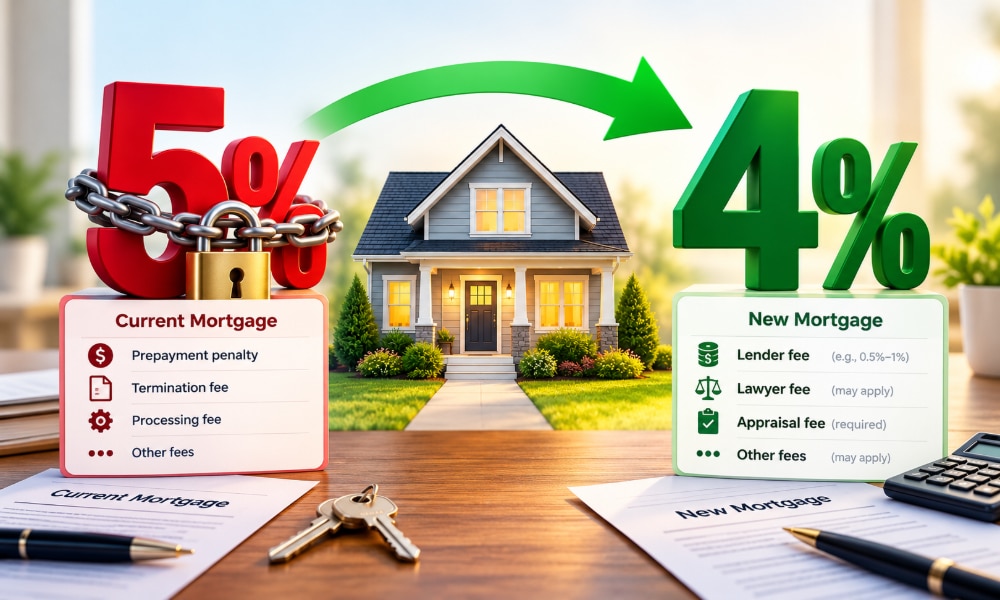
You signed a mortgage at 5.00%. A little later, another lender offers you 4.00%. Should you break your mortgage and switch?
Maybe yes. Maybe no. Lower interest could save thousands, but the prepayment penalty, legal fees, appraisal, lender fees and other expenses could cost even more. Sometimes switching is worth paying those fees; sometimes it is not. The answer depends on the actual numbers, not how attractive the advertised rate looks.
Principal Is Not the Same as Interest
Before we compare mortgages, we need to understand one fundamental difference: principal is the money you borrow, while interest is the cost of borrowing it for as long as you owe it.
Let me explain with a simple example.
Imagine Borrowing $100 From a Friend
Suppose your friend lends you $100 and says:
Here is what happens if you make no payments:
| Time After the First Month | Total Amount Owed |
|---|---|
| Immediately | $100 |
| After 1 week | $101 |
| After 5 weeks | $105 |
| After 52 weeks | $152 |
Notice something important: the original $100 never disappears.
Your friend lent you $100, and you still owe that $100. Unless your friend agrees to forgive part of the debt, you cannot make it disappear simply by waiting.
But the extra money is different.
That additional $1 per week is the cost of borrowing. In this simplified example, paying back the $100 before the weekly charges begin would avoid those charges entirely.
Now Apply This to Your Mortgage
Your mortgage works on the same basic principle, except that mortgage interest is calculated on your outstanding balance rather than as a fixed $1 weekly charge.
As you repay principal, your mortgage balance falls, and there is less money on which future interest can be charged.
That is why a lower monthly payment does not automatically mean you are saving money. You might simply be repaying your principal more slowly.
Why This Matters When Switching Mortgages
When you switch lenders, your outstanding principal does not magically disappear. You still owe that money, now under a different mortgage.
What may change is the amount of interest you pay, along with the penalties and fees involved in switching.
That is why my Break Early vs Stay Mortgage Comparison Calculator focuses on comparing interest costs and switching expenses. It also tracks the remaining principal balances because they affect future interest, but it does not treat differences in principal repayment or remaining mortgage balances as interest savings.
Repaying principal reduces what you owe.
Reducing interest reduces what borrowing costs you.
This is the foundation of everything we calculate next. When comparing two mortgages, we must not mistake principal repayment for savings. Our goal is to determine how much interest we can save, and whether those savings are greater than the penalties and fees required to switch.
First, Get the Actual Figures From Your Lender
A precise comparison starts with reliable inputs. Guessing the prepayment penalty or forgetting a lender fee can completely reverse the answer. That is why I built a copy-ready lender email directly into the calculator. You do not have to figure out what to ask for.
- Open the calculator and click “Show email example.”
- Click “Copy email example.” Paste the message into an email to your existing mortgage lender, add your details and proposed break date, and send it.
- Ask for a written breakdown: the mortgage balance on that date, your interest rate and payment details, the official prepayment penalty, and all discharge, processing and other lender fees.
- Get a quote for the new mortgage, including its rate, payment, amortization, appraisal, legal and lender fees. Enter the figures in the calculator and click Calculate.
Start with one email. The calculator already has the template; simply copy, personalize and send it. The more accurate your lender's figures, the more useful the comparison.
Open the calculator and copy the lender email →The lender must confirm the figures for your chosen break date. Penalties and balances can change with the date, and the template requests an itemized response so costs are easier to check.
Let's Compare Two Choices Using the Same Mortgage
Let's look at an example mortgage that started on May 8, 2023. The details below are the default values used in my Break Early vs Stay Mortgage Comparison Calculator, so you can follow the calculations and try the same example yourself.
We'll compare keeping this mortgage with breaking it on March 15, 2026, and switching to a new mortgage at a lower interest rate.
Started: May 8, 2023
Original loan: $603,135.00
Original amortization: 25 years
Original term: 5 years
Rate: 5.00% fixed
Monthly payment: $3,507.86
Maturity date: May 8, 2028
On the proposed break date of March 15, 2026, the example's payout balance is $568,237.07. The current mortgage has 20 years of amortization remaining at maturity.
| Mortgage comparison | Option 1: Stay | Option 2: Switch |
|---|---|---|
| Mortgage balance / new principal | $568,237.07 payout figure | $568,237.07 |
| Interest rate | 5.00% fixed | 4.00% fixed |
| Payment | $3,507.86/month | $2,983.23/month |
| Payment frequency | Monthly | Monthly |
| Amortization | 20 years remaining at existing maturity | New 25-year schedule |
| Calculation begins | March 15, 2026 | March 15, 2026 |
| Comparison ends | May 8, 2028 | May 8, 2028 |
Why stop on May 8, 2028? That is the current mortgage's maturity date. Using the same end date prevents us from pretending to know what renewal rates will be years into the future. The replacement mortgage may continue beyond that date, but its later costs are outside this comparison.
Step 1: Calculate the Interest If You Stay
We keep the existing mortgage at 5.00% and project its interest from the break date through May 8, 2028, using the entered payment of $3,507.86 per month.
The calculator accounts for the entered last payment date (March 1, 2026), estimated accrued interest in the payout figure, the initial partial period, each scheduled payment, and the final partial period.
Step 2: Calculate the Interest If You Switch
Now imagine refinancing the same $568,237.07 payout amount at 4.00% fixed, with a new 25-year amortization and an entered monthly payment of $2,983.23.
We calculate only to May 8, 2028, the same end date as the stay option.
The difference in projected interest is:
Saving more than $11,500 in interest sounds compelling. But we have not yet paid to get out of the first mortgage or set up the second one.
Step 3: Add Every Cost of Switching
Breaking a mortgage can involve an official lender prepayment penalty, discharge or processing charges, and costs to arrange the replacement loan. The Financial Consumer Agency of Canada (FCAC) recommends checking both penalties and other switching fees before deciding.
Existing mortgage: penalty and fees
| Cost | Amount |
|---|---|
| Prepayment penalty | $8,500.00 |
| Termination fee | $400.00 |
| Processing fee | $300.00 |
| Other fees | $75.00 |
| Current mortgage exit costs | $9,275.00 |
New mortgage: setup costs
| Cost | Amount |
|---|---|
| Appraisal fee | $700.00 |
| Lawyer fee | $2,000.00 |
| Lender fee: 1% × $568,237.07 | $5,682.37 |
| Other fees | $40.00 |
| New mortgage setup costs | $8,422.37 |
For this illustration, the calculator uses the $8,500 prepayment penalty entered by the user. It does not invent or automatically calculate the lender's official penalty. In a real transaction, request a written payout statement for the proposed date and obtain actual setup quotes.
Step 4: Let the Numbers Decide
The decision calculation is straightforward:
Even though the new rate is a full percentage point lower, the switching costs exceed the projected interest savings by $6,188.49 under this calculator's method. You would not break the mortgage purely for this offer.
What If the Calculator Shows Only $500 in Savings?
Even a positive number does not always mean the effort is worthwhile. Imagine that, after every expected fee, the projected benefit of switching is only $500. An extra legal charge or a change in the final payout amount could erase that entire amount. You may reasonably decide that $500 is not enough to justify changing providers.
My calculator reflects that practical distinction with a $1,500 decision threshold:
Switching is not recommended by the interest-and-fees calculation.
Switching shows a small potential benefit. Think carefully about uncertainty and effort.
The calculator says you should switch on the entered figures, subject to the mortgage's full terms.
This $1,500 figure is a practical threshold chosen for this calculator, not a banking rule. Your own comfort level, mortgage flexibility and risks still matter. Its purpose is to avoid treating every small positive number as an automatic green light.
How Does the Calculator Get Such Detailed Interest Figures?
Instead of estimating the result by multiplying an interest-rate difference by the mortgage balance, it uses a payment schedule. For fixed-rate examples it converts Canada's nominal semi-annual compounding convention into effective periodic rates, considers initial and final partial periods, and reduces principal as scheduled payments are applied.
Here is the actual interest mathematics
For fixed-rate mortgages in this example, the annual rate is compounded semi-annually before being converted into the daily and monthly rates used by the model:
For the first 17 days from March 15 to April 1, the calculator then estimates:
Subsequent scheduled monthly interest entries use the equivalent monthly rate and the declining principal balance after payments. That is how each row of the comparison is built up to maturity.
The original payout example includes a March 1 last-payment date. Under its accrued-interest assumption, the calculator derives approximately $567,135.82 of starting principal for the existing mortgage calculation, while the proposed mortgage begins at the stated $568,237.07 amount. This is one reason actual lender payout details matter.
| Selected interest entry | Stay: 5% | Switch: 4% |
|---|---|---|
| April 1, 2026: initial partial period | $1,337.24 | $1,069.22 |
| May 1, 2026: scheduled payment period | $2,338.82 | $1,878.53 |
| May 1, 2028: scheduled payment period | $2,217.46 | $1,787.47 |
| May 8, 2028: final partial period | $520.80 | $418.00 |
| All interest entries combined | $58,835.47 | $47,326.59 |
The entries between these dates are not skipped in the calculation. Every period is included in the totals. Here is the full dated breakdown from the Version 5.4 default example:
Show the complete 27-entry interest comparison
| Interest date | Stay: 5% | Switch: 4% |
|---|---|---|
| Apr 1, 2026 | $1,337.24 | $1,069.22 |
| May 1, 2026 | $2,338.82 | $1,878.53 |
| Jun 1, 2026 | $2,334.00 | $1,874.88 |
| Jul 1, 2026 | $2,329.16 | $1,871.21 |
| Aug 1, 2026 | $2,324.30 | $1,867.54 |
| Sep 1, 2026 | $2,319.42 | $1,863.85 |
| Oct 1, 2026 | $2,314.52 | $1,860.15 |
| Nov 1, 2026 | $2,309.59 | $1,856.44 |
| Dec 1, 2026 | $2,304.65 | $1,852.71 |
| Jan 1, 2027 | $2,299.69 | $1,848.97 |
| Feb 1, 2027 | $2,294.71 | $1,845.22 |
| Mar 1, 2027 | $2,289.71 | $1,841.46 |
| Apr 1, 2027 | $2,284.68 | $1,837.69 |
| May 1, 2027 | $2,279.64 | $1,833.90 |
| Jun 1, 2027 | $2,274.57 | $1,830.10 |
| Jul 1, 2027 | $2,269.49 | $1,826.29 |
| Aug 1, 2027 | $2,264.38 | $1,822.46 |
| Sep 1, 2027 | $2,259.25 | $1,818.63 |
| Oct 1, 2027 | $2,254.10 | $1,814.78 |
| Nov 1, 2027 | $2,248.93 | $1,810.91 |
| Dec 1, 2027 | $2,243.74 | $1,807.04 |
| Jan 1, 2028 | $2,238.53 | $1,803.15 |
| Feb 1, 2028 | $2,233.29 | $1,799.25 |
| Mar 1, 2028 | $2,228.04 | $1,795.33 |
| Apr 1, 2028 | $2,222.76 | $1,791.41 |
| May 1, 2028 | $2,217.46 | $1,787.47 |
| May 8, 2028 | $520.80 | $418.00 |
| Total projected interest | $58,835.47 | $47,326.59 |
These are the calculator's modelled interest entries, not a bank-issued amortization statement. Payment dates, daily accrual and payout conventions can differ among lenders.
What About the Lower Monthly Payment?
The proposed monthly payment is $524.63 lower ($3,507.86 versus $2,983.23). That can help monthly cash flow, but $524.63 is not the amount of interest saved each month. It also reflects a new 25-year amortization and a different rate of principal repayment.
By May 8, 2028, the calculator shows a remaining balance of approximately $536,416.75 in the stay calculation and $539,495.69 in the switch calculation. Those are debts still owed, not extra fees. They are displayed for transparency, not subtracted as if one borrower's principal repayment were an interest expense.
Because the two payment paths and balances differ, a full economic comparison may also consider cash-flow timing, the outstanding balances, financing of fees, and what happens after the existing term ends. This article isolates the interest-and-fees question through May 8, 2028, which is what the calculator's recommendation measures.
What If Some Switching Fees Disappear?
Fees can change the outcome. Suppose the same proposed 4% mortgage comes with its 1% lender fee waived. Total switching costs would fall by $5,682.37, from $17,697.37 to $12,015.00.
The interest savings would still be $11,508.88. So the model would still show a $506.12 shortfall. Even eliminating a major fee does not quite make this particular example worthwhile.
Now change the fee assumption further, just to see how sensitive the answer is. If total switching costs were $9,000 instead of $17,697.37, while the same projected interest figures remained, the result would be:
That is a hypothetical change in fees, not a new lender quote. It proves the point: the calculator is not designed to tell everyone to stay. With enough interest savings after costs, switching can make financial sense.
Does It Matter How Early You Switch?
Absolutely. Timing changes the opportunity. Suppose you take a five-year fixed mortgage and a meaningfully lower rate appears just two or three months later. There may be almost five years of interest payments left in which a lower rate could make a difference. It is worth doing the calculation now, not automatically waiting years for renewal.
If there are only a few months left before maturity, the potential interest savings over that short period may be too small to offset legal fees, other costs and the prepayment penalty. Waiting until renewal may be better. But these are tendencies, not guaranteed outcomes: the penalty itself can also change with the remaining term, so there is no universal rule that switching early is always best or switching late is never worthwhile.
Know Your Penalty Before You Decide
Depending on the mortgage contract, a closed fixed-rate mortgage's prepayment penalty is commonly based on the greater of three months' interest and an interest rate differential (IRD). The lender's own agreement and calculation determine the amount. Penalties can run into thousands of dollars.
That is why the copyable email template matters. The calculator does not pretend to know your lender's official penalty. It helps you obtain the figure directly from the source, then compares it with the interest you could avoid and all the costs you would actually face.
One important detail: if the lender's payout quote includes accrued interest or fees in the balance, check what is included to avoid double-counting. Also confirm whether any fees will be paid upfront or added to the new mortgage. The calculator's interest-and-fees view does not independently model the financing cost of rolled-in fees.
The Bottom Line
- One percentage point lower: 5.00% to 4.00% fixed.
- $11,508.88: projected interest avoided through the existing maturity.
- $17,697.37: assumed penalties and switching costs.
- $6,188.49: amount by which switching costs exceed interest savings.
- Stay: the calculator's recommendation for these exact inputs.
- $1,500: the calculator's practical threshold for recommending a switch.
I am not against breaking a mortgage early. I am against doing it without knowing the numbers. If interest savings significantly exceed all the costs, even switching early in a five-year term may make sense. If they do not, an attractive new rate may still be the wrong move.
Principal is principal. Interest is where the saving opportunity lies. Paying principal down faster reduces future interest, but a smaller payment is not the same as money saved. Focus on interest, get every fee in writing and use the calculation to decide.
Do not chase the lowest advertised rate. Compare what the mortgage will actually cost you.
This historical example uses the default inputs from the Break Early vs Stay Mortgage Comparison Calculator (Version 5.4). Its interest totals are modelled using the specified rates, payment amounts, payment dates and lender payout assumption. Both fixed rates are held constant during the March 15, 2026 to May 8, 2028 comparison. Fees are entered example amounts, not independently verified lender quotes. Different lender methods, unexpected expenses, financing of fees, future variable-rate changes, renewals and interest accrual conventions may produce different outcomes. The $1,500 switching threshold is a chosen decision rule, not an industry requirement. This calculator compares projected interest and listed switching costs; it is not a complete discounted-cash-flow or lifetime mortgage-cost assessment and does not guarantee a financial outcome.
FCAC: Mortgage prepayment penalties
FCAC: Breaking your mortgage contract
FCAC: Mortgage renewal and switching costs
Should You Break Your Mortgage or Stay?
Step 1: Open the calculator and copy the ready-made email to request official figures from your lender.
Step 2: Enter your current mortgage, proposed new mortgage and every switching cost.
Step 3: See the projected interest, detailed breakdown and Stay / Small Benefit / Switch recommendation.
A Mortmatics™ Calculator by Sukru
