Why Accelerated Weekly Is the Only Payment Frequency I Highly Recommend
Published on October 13, 2026
Your goal should be simple: own your home sooner, become mortgage-free faster, and keep more of your money instead of paying it to the lender as interest.
That is why I recommend accelerated weekly payments. Canadian lenders offer several payment frequencies, but they do not produce the same result. The numbers below show the difference.
There Are 6 Payment Frequencies
The first four mainly change when you pay. Accelerated payments change something more important: how much you pay toward the mortgage each year.
Here Is the Math
Let me show you why I recommend accelerated weekly as the mortgage payment method you should choose. We will use one simple example and follow the money for a full year.
Mortgage amount: $500,000
Interest rate: 5%
Amortization: 25 years
Monthly payment: $2,908.02
First, Look at Regular Monthly Payments
With monthly payments, you pay $2,908.02 twelve times each year.
So a regular monthly payment schedule means you make $34,896.24 in mortgage payments each year.
Now Let's Look at Accelerated Weekly
Accelerated weekly starts with the exact same monthly payment, but divides it by four:
Now comes the most important part. A month is not the same as four weeks. Four weeks is only 28 days, while most months have 30 or 31 days.
If there were exactly four weeks in every month, 12 months would contain only 48 weeks:
But a weekly mortgage schedule has 52 payments per year, not 48. Those four additional weekly payments are exactly what creates approximately one extra monthly payment each year.
And those four extra weekly payments add up to one entire monthly payment:
That is essentially the same as the regular monthly payment of $2,908.02. The two-cent difference is simply caused by rounding the weekly payment to the nearest cent. That is why accelerated weekly effectively gives you 13 monthly-payment equivalents each year instead of 12.
Comparing Annual Payments
Now let’s compare the two annual payment amounts:
$2,908.02 × 12 = $34,896.24 per year
Accelerated Weekly
$2,908.02 × 13 = $37,804.26 per year
Difference: one extra $2,908.02 monthly payment every year.
You may notice that $727.01 × 52 gives $37,804.52 instead of $37,804.26. That small 26-cent difference happens because the weekly payment shown here is rounded to the nearest cent.
The important point is simple: accelerated weekly turns 12 monthly payments into the equivalent of 13 monthly payments every year.
What Does the Extra Payment Really Cost?
We are comparing regular monthly payments with accelerated weekly payments. Because one is paid monthly and the other weekly, we cannot simply compare $2,908.02 with $727.01.
We first need to put them on the same scale using our math knowledge.
We already calculated above that regular monthly payments total $34,896.24 per year. If we spread that same annual amount across 52 weeks, it works out to:
So $671.08 per week is simply the weekly equivalent of the regular monthly payment schedule. It is not changing our comparison. We are still comparing monthly with accelerated weekly.
We also already calculated above that accelerated weekly is $727.01 per week. Now we can compare the two on the same weekly scale, so the difference is:
You are not suddenly making one large extra payment of $2,908.02. On a weekly-equivalent basis, the regular monthly payment works out to $671.08 per week, while accelerated weekly is $727.01 per week.
That is only about $55.93 more per week. Accelerated weekly spreads approximately one additional monthly payment across the entire year.
So now let’s look at what paying that extra $55.93 per week can actually do to your mortgage.
What Does an Extra $55.93 Per Week Do?
That extra money goes toward your mortgage sooner, your balance falls faster, and the lender has less principal on which to charge interest.
| Payment Method | Approx. Payment | Payments / Year | Approx. Paid / Year | Approx. Payoff |
|---|---|---|---|---|
| Monthly | $2,908.02 | 12 | $34,896 | 25y, 0m, 0w |
| Semi-Monthly | $1,454.01 | 24 | $34,896 | 24y, 11m, 2w |
| Bi-Weekly | $1,342.17 | 26 | $34,896 | 24y, 11m, 2w |
| Weekly | $671.08 | 52 | $34,896 | 24y, 11m, 0w |
| Accelerated Bi-Weekly | $1,454.01 | 26 | $37,804 | 21y, 6m, 0w |
|
Accelerated Weekly
Recommended |
$727.01 | 52 | $37,804 | 21y, 5m, 2w |
Monthly: about 25 years.
Accelerated weekly: about 21 years and 5 months.
You could be mortgage-free about 3½ years sooner.
And Then Look at the Interest
Paying the mortgage sooner also means the lender has less time to charge you interest.
You do not need to memorize every number in this next table. Pay special attention to the Total Interest, Total Saved, and Approx. Payoff columns.
| Payment Method | 3-Yr Interest | 3-Yr Saved | 5-Yr Interest | 5-Yr Saved | Total Interest | Total Saved | Approx. Payoff |
|---|---|---|---|---|---|---|---|
| Monthly | $71,926 | $0 | $117,019 | $0 | $372,407 | $0 | 25y, 0m, 0w |
| Semi-Monthly | $71,810 | $116 | $116,816 | $203 | $370,638 | $1,769 | 24y, 11m, 2w |
| Bi-Weekly | $71,801 | $125 | $116,800 | $219 | $370,502 | $1,905 | 24y, 11m, 2w |
| Weekly | $71,748 | $178 | $116,706 | $313 | $369,688 | $2,720 | 24y, 11m, 0w |
| Accelerated Bi-Weekly | $71,131 | $795 | $114,863 | $2,156 | $311,972 | $60,436 | 21y, 6m, 0w |
|
Accelerated Weekly
Recommended |
$71,073 | $853 | $114,761 | $2,258 | $311,285 | $61,122 | 21y, 5m, 2w |
Keep Around $60,000. Do Not Pay It to the Banks.
This is the number I want you to remember.
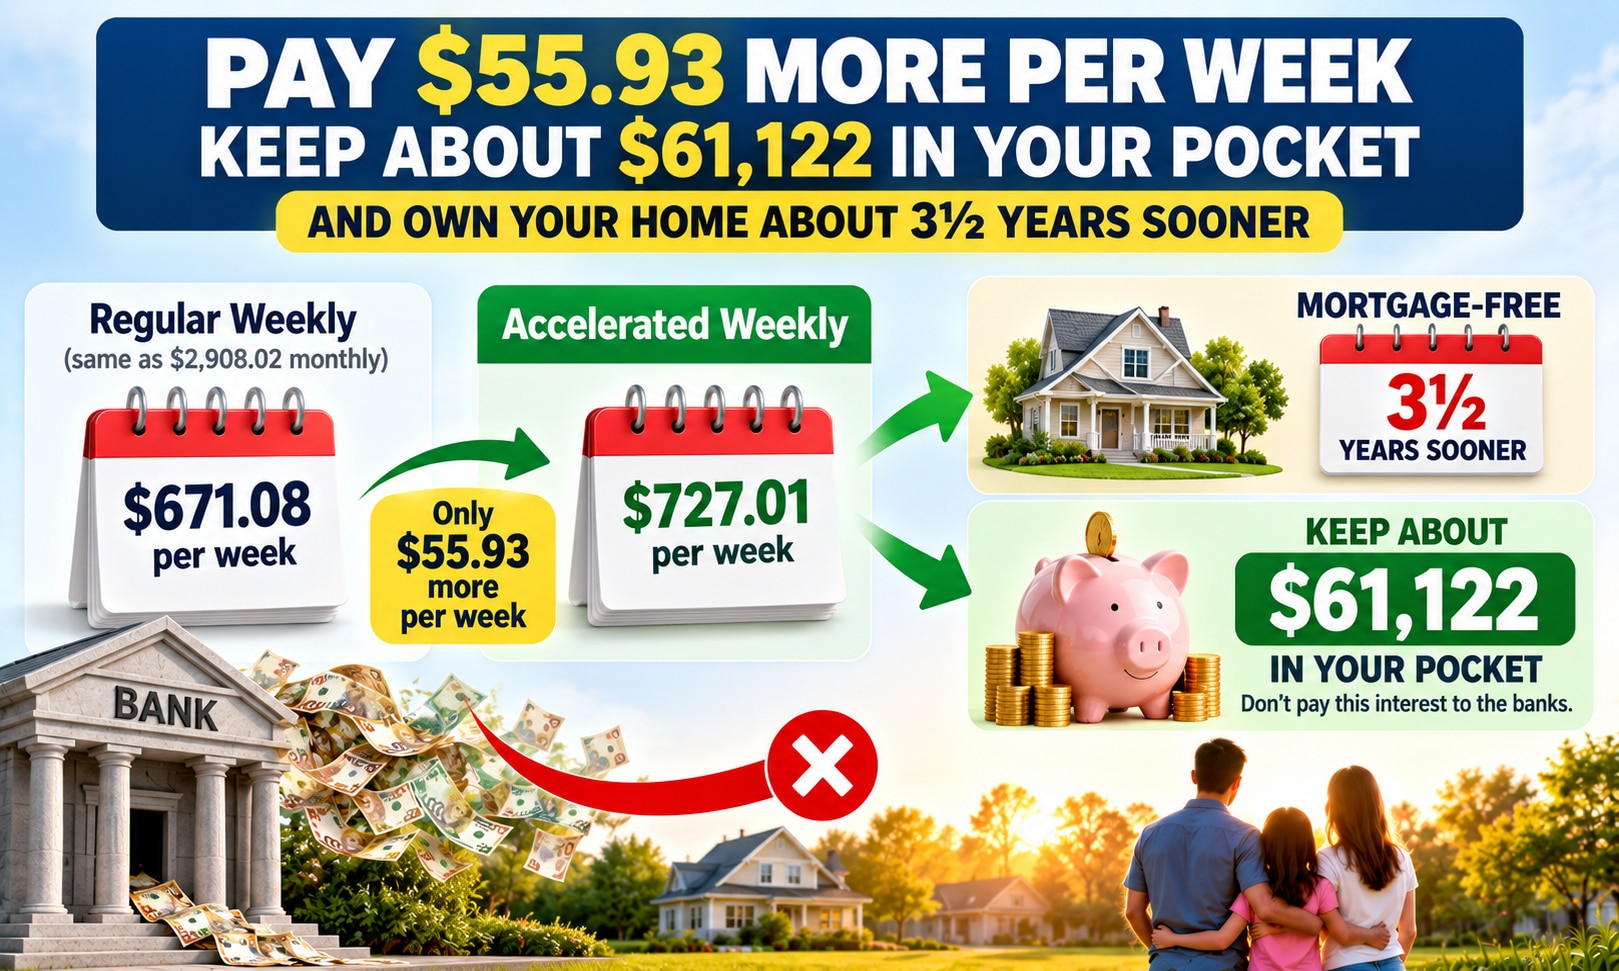
In this example, paying $55.93 more per week through accelerated weekly payments reduces estimated lifetime interest by about $61,122.
That is money that does not have to become interest paid to the lender. Instead, you are putting more money toward your own home and getting rid of the mortgage sooner.
- $55.93 more per week
- About 3½ years sooner to become mortgage-free
- About $61,122 less interest in this example
Why Accelerated Weekly and Not Accelerated Bi-Weekly?
Accelerated bi-weekly is very close, and it also produces major savings. But accelerated weekly is still the most efficient result in this example.
It pays the mortgage more frequently, finishes slightly sooner, and produces the lowest total interest of all six payment methods. If I am choosing between the six, I choose accelerated weekly.
Accelerated Weekly Is a Payment Choice, Not a Different Mortgage
One important thing to understand is that accelerated weekly is not a different mortgage that requires a separate mortgage approval. It is simply one of the payment-frequency options that may be available with your mortgage.
There are six common mortgage payment frequencies: monthly, semi-monthly, bi-weekly, weekly, accelerated bi-weekly, and accelerated weekly. You are still dealing with the same mortgage. You are choosing how often you want to make your payments, subject to the payment options offered by your lender and mortgage product.
You get your mortgage approved, and then choose from the payment frequencies available with that mortgage.
Weekly Payments Can Also Be Easier to Manage
There is another practical reason I like accelerated weekly payments: the smaller, more frequent payment can be easier to manage.
In our example, a monthly payment means making sure you have $2,908.02 available when the monthly mortgage payment comes out.
With accelerated weekly, you are managing approximately $727.01 each week instead. Rather than preparing for one large payment every month, you can make sure the smaller amount is available each week.
I find that much easier to plan around. It can also line up naturally with the way many people receive and manage their income.
Paying More Frequently Helps a Little Too
There is also a smaller mathematical advantage to paying more frequently. When part of your mortgage principal is paid earlier, the outstanding balance becomes slightly lower sooner.
That means there is slightly less principal left for future interest calculations. The difference is much smaller than the benefit created by making the equivalent of one extra monthly payment each year, but over time, those small differences can still add up.
That is why, even before acceleration is considered, paying the same approximate annual amount weekly can produce slightly less interest than paying it monthly.
Build Your Budget Around It
Do not start by asking which payment schedule feels easiest. Start by asking how quickly you can pay off your mortgage, pay less interest, and own your home outright.
When deciding how much mortgage you can afford, include the accelerated weekly payment in your budget from the beginning. The goal is not to carry a mortgage comfortably for 25 years. The goal is to pay less interest, become mortgage-free sooner, and own your home outright.
Use Prepayment Privileges Too
Accelerated weekly payments do not have to be the end of the strategy. Depending on your mortgage agreement, you may also be able to increase regular payments or make lump-sum payments directly toward the principal. Check your lender's prepayment limits before making additional payments.
The Bottom Line
Your goal should be to own your home sooner, become mortgage-free faster, and pay as little interest as possible.
In this $500,000 example, choosing accelerated weekly instead of monthly means paying only about $55.93 more per week, but can make the mortgage disappear roughly 3½ years sooner and reduce estimated lifetime interest by about $61,122.
- Pay Less Interest: In our $500,000 example, accelerated weekly reduces estimated lifetime interest by about $61,122 compared with monthly payments.
- Become Mortgage-Free Sooner: The mortgage is paid off about 3½ years sooner.
- Only $55.93 More Per Week Is Manageable: Instead of finding one large extra payment of $2,908.02, accelerated weekly spreads approximately that extra amount across the year, working out to only about $55.93 more per week.
- Smaller Weekly Payments Can Be Easier to Manage: Instead of preparing for a $2,908.02 monthly payment, you manage approximately $727.01 each week.
- Pay Down the Principal Sooner and More Frequently: More frequent payments reduce your outstanding mortgage balance sooner, leaving slightly less principal for future interest calculations.
- Get the Best Result of All Six Payment Options: In our example, accelerated weekly produces the lowest total interest and the fastest mortgage payoff of all six payment frequencies.
Because of all the reasons above, I highly recommend accelerated weekly mortgage payments.
Mortgage payment-frequency definitions are based on guidance from the Financial Consumer Agency of Canada (FCAC). Calculations and savings shown in this article are illustrative estimates based on the example provided and may vary by lender, mortgage product, payment dates, interest rates, renewal rates, and prepayment terms.
Financial Consumer Agency of Canada →
See What Accelerated Weekly Could Save You
Use my Mortgage Payment & Amortization Calculator to compare your payment options and see how accelerated weekly could affect your interest cost and mortgage payoff time.
Calculate My Savings →